Business Planning
- for liquidity a special cash flow is needed
It is favourable to already think about business planning while analysing a company. This avoids any barriers between analysis and planning. For example, you can use the same loan list for the past as for the future.
Therefore, the connection between analysis and planning was already shown on page Home/Why is this website interesting for you? Now, it is presented again, as part of my programme JUP PS.
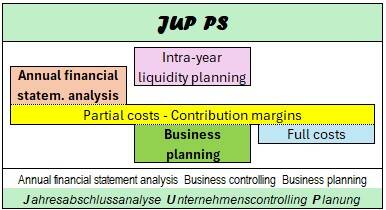
First let’s talk about intra-year liquidity planning
Intra-year liquidity planning- with a special cash flow
If the sustainable cash flow 3 is sufficiently high — i.e. above the reinvestment level — there is no need to consider short-term financial planning. It’s very time-consuming. However, if the cash flow 3 is not sufficiently high (or even negative), this point becomes an issue. See following table.
In intra‑year liquidity planning the Self-financing Capacity (‘Cash flow 3 from own economic forces’) must be followed by a cash flow, which includes extraordinary payments. It has been more than 20 years since the author called it ‘Cash flow 3 incl. non-periodic and non-sustainable payments’. Now the author would call this special cash flow simply Cash flow 4.
Still, investments and new loans follow below this special Cash flow.
A large intra-year liquidity plan along these lines is integrated into the JUP PS programme. The principle is all that matters here.
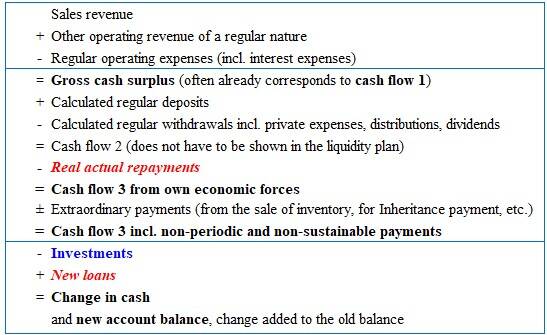
A similar approach may be applied to year-on-year planning if the reason for it is financial difficulty. In this case, extraordinary payments to or from outside the company really have a significant impact.
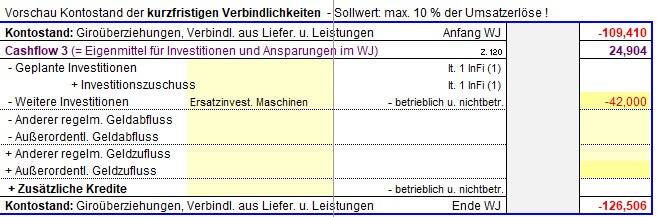
In addition, do not forget the evolution of the current liabilities balance including the trade payables.
If you select the year-after-year option in JUP PS, a special table on current liabilities balance will open. Perhaps a table like the following suits you. This table begins with the short-term debts at the start of the year, to which sustainable cash flow 3 must be added. Then the planned investments must be deducted, including estimates for the unexpected replacement of machinery and equipment. Are there any cash inflows or outflows that were not included in cash flow 3? Last, the planned additional long-term loans must be taken into account.
The table concludes with the short-term debts at the end of the year. Such a table will be easy for entrepreneurs to understand.
Operational medium-term planning
Students may find the analysis challenging. However, their planning is relatively straightforward later on - if the planning tables are presented in the same way.
There are many more facets of operational planning than can be covered on this website. That is why I am referring you to my PDF,
'i Business Management: Basics, Indicators, Examples.PDF'.
At the beginning of the planning process, it should be clear what will be compared. If you want to compare alternative developments of the company, this can be expressed like this :
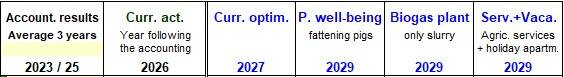
In this mode, you begin by calculating the current year, after which you can start exploring the alternatives. In between, you may then plan an 'optimised' variant with only a few investments.
Examples showing the target alternatives:
1. Making changes to the existing fattening pigs to improve their well-being.
2. Building an additional biogas plant on the farm.
3. Providing machinery services and holiday accommodation.
The year-after-year' scheme is often to be preferred:
This method is particularly helpful in cases of financial difficulty or when companies are facing major changes to their business model, such as the transition from conventional to ecological production in agriculture. About 50% of cases calculated by consultants working with JUP PS are using this method. The year-after-year model is similar to dynamic planning.
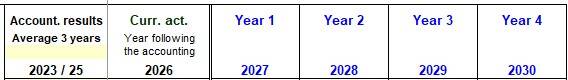
Within JUP PS, you can switch over. When switching, the programme must make significant changes to the loan lists. This is because, in the year-on-year scheme, each loan value must be based on the previous year.
Which year should you use for the "Current Actual" column?
In textbooks, you will mostly not find any proposals for starting dates. However, in real practice, this is crucial. If you are not careful enough, you will calculate the repayments a whole year or more too early.
See the PDF 'i Business Management - Basics, Indicators, Examples'.