Liquidity and Cash flows
Business management literature is full of advice for entrepreneurs, for example on how to start a business. A wide range of terms can be found. However, the indicators whether the business runs or not, often take a back seat. Here are the three main terms and the questions associated with:
Profitability:
Are labour, capital and other resources adequately rewarded ?
Liquidity:
Is enough cash available throughout the year ?
Stability:
Is the existential basis strong enough to survive difficult periods ?
The file 'i Business Management - Basics, Indicators, Examples.pdf' contains informations on profitability and stability.
Let's focus here on liquidity.
This paper will focus solely on periodic liquidity, more exactly to the cash flows. A good understanding of cash flows can help to avoid liquidity problems and even bankruptcy.
Cash flow 1–3
Cash flow 1-3 form a cascade. Entrepreneurs may ask:
- how much cash the business generates from operations,
- how much remains after private deposits and withdrawals/dividends,
- how much is left for investment after repayments of debts.
Cash flows 1–3 are derived from four classes of double-entry bookkeeping.. This is the cash flow system that most closely resembles accountancy.
- Profit accounts → Gross cash surplus
- Private accounts → Adjusted deposits / adjusted withdrawals
- Financial accounts → Repayments
- Tangible asset accounts → Depreciation benchmarks
The following diagram shows the whole cascade.
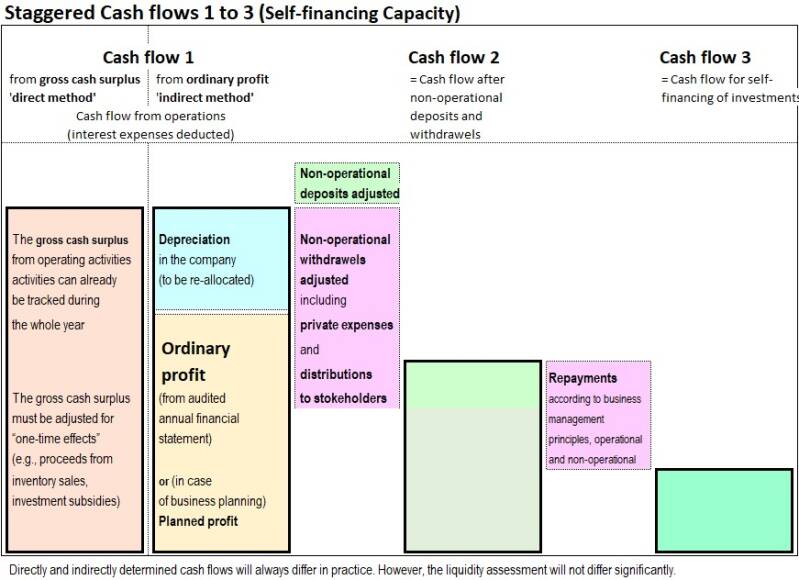
Cash flow 1 — Operational cash flow
Two starting points:
=> Gross cash surplus from the profit accounts (direct method).
=> Ordinary profit + depreciation (indirect method, practitioner's formula).
Adjustments for Cash flow 1
To obtain a sustainable operational cash flow, extraordinary items must be removed:
- one‑time payments (inheritance payments, land sales, accident compensations)
- non‑periodic receipts
- accidental events
- non‑operational items
This ensures that Cash flow 1 reflects normal business operations, without exceptional events.
Cash flow 2 — Cash flow after adjusted withdrawals and deposits
Cash flow 2 starts with Cash flow 1 minus adjusted withdrawals including distributions, plus deposits. Withdrawals and deposits do not arise from the analysed business activity.
Initially, all cash transactions to and from private savings accounts should be deducted from the total deposits and withdrawals figure.
Depending on the organisation, withdrawals and deposits are handled differentl
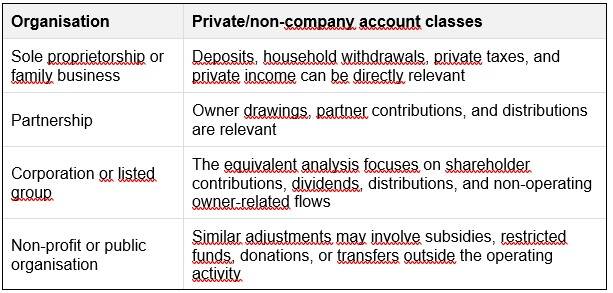
In principle, you can also find deposits in big companies, such as from rented residential properties or photovoltaic panels, which do not belong to the analysed company. If there is no need for reinvestment, the entrepreneur can even use positve funds for cross-financing. There are also organisations that regularly benefit from subsidies, e.g. from churches.
Cash Flow 2 starts with Cash Flow 1 and adjusts for private withdrawals, distributions, and non-operating deposits that do not arise from the analysed business activity.
Adjusted deposits
Non‑operational inflows that support the entrepreneur/owner:
- rental income
- interest from private accounts
- additional work
- other private earnings
Adjusted withdrawals
Non‑operational outflows:
- household expenses
- private insurance
- private taxes
- dividends and distributions on shareholders
Withdrawals can also be withdrawals in kind, e.g. in farms.
Cash flow 3
= Cash flow for self‑financing of investments = Self-financing capacity
Recorded repayments describe what happened during the period; adjusted repayments are used to assess what the business can sustainably bear.
Cash flow 3 = Cash flow 2 — sustainable repayments
This step requires careful analysis:
- repayment deferrals
- unscheduled repayments
- debt restructuring
- fixed‑rate mortgages without repayments
- repayment suspensions
- refinancing effects
Benchmarks for Cash flow 3 — Depreciations as the Key Metric
You can compare Cash Flow 3 with depreciation as benchmarks. You can differentiate between long-term and medium-term assessments.
Long term benchmark: Total depreciation.
Medium term benchmark: Depreciation of machinery and perennial crops.
Buildings usually require no reinvestment for 15+ years.
The Cash flow 3, measured against depreciation, is not just an "early warning system." It is also a simple, teachable concept.
Yet, cash flow 3 must be interpreted carefully under inflation. In countries with high inflation, reinvestment costs may be far above depreciation.
The 'debt service limits' (see below) are often measured by the 'utilization of the debt service limit percentage'. The 'reinvestment coverage percentage' reflects this.
Comparison of Cash flows
Caution! Many cash flow developers have their own definitions!
Cash flow 1-3
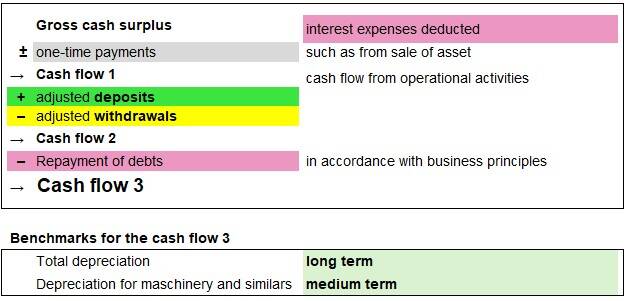
For entrepreneurial liquidity analysis, I consider Cash flow 1–3 cascade more informative than several commonly used cash-flow measures:
- respects the four account classes
- shows sustainable liquidity
- shows self‑financing capacity
- works for SMEs and large groups
- works for planning and analysis
- works internationally
Free Cash flow
- ignores deposits and withdrawals
- starts from unadjusted profit
- can be misleading when investments fluctuate
- does not respect the four account classes
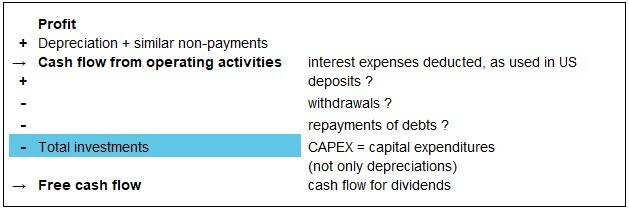
Consequences:
a) If investments are minor, the company can pay huge withdrawals such as dividends.
b) If investments are high, no or few dividends/withdrawals can be paid.
Can an entrepreneur think in that way?
Nevertheless, even groups like the German ZF apply it.
Retained Cash flow
- ignores non‑company deposits
- ignores private withdrawals beyond dividends
- uses profit instead of ordinary profit
- not compatible with double‑entry logic
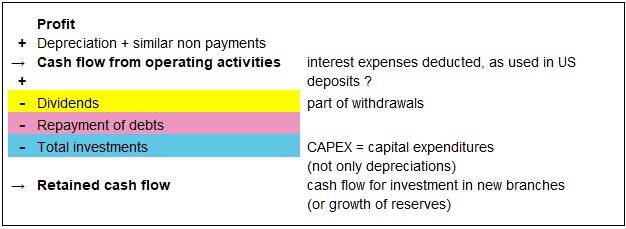
Retained cash flow indicates the amount of cash remaining after total investment in existing activities.
Debt Service Limits
- Long‑term version deducts total depreciation
- Medium‑term version deducts machinery depreciation
- Benchmark fully integrated, see Cash flow 3 benchmarks
- Developed by agricultural experts. It should be replaced by Cash flow 3.
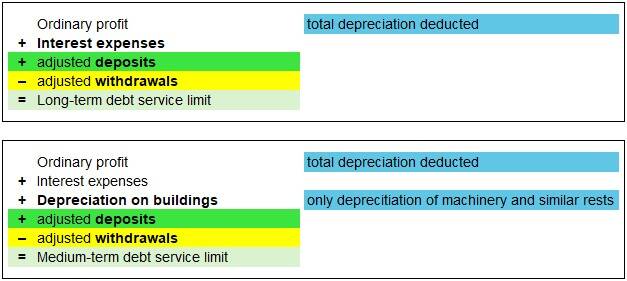
The question of ‘cash flow 3’ is:
Is there enough left for investments - after repayment? '
The question of 'debt service limits' is:
Is there enough left for the banks – after reinvestment (depreciation)?
As you can see, ‘Cashflow 3’ and its reference values, as well as the ‘debt service limits’, raise mirror-image questions.
The two decisive metrics are the same:
-> the total depreciation and
-> the depreciation of machinery (and assets with a similar service life, such as perennial crops in agriculture).
The cascade cash flow 1-3 can also be applied in business planning. But if you plan for a company, which faces big financial difficulties, see the section Intra-year liquidity planning on the page of business planning.
Other terms containing 'cash flow'
Discounted cash flow
Although the discounted cash flow is a useful concept, it can only be used for future calculations. It involves discounting the estimated cash flows for subsequent years to their present value using financial mathematics. Therefore, discounted cash flow is not a means of analysing annual financial statements. It is just for planning! It shows profitability more than liquidity.
Cash flow statement
The cash flow statement is the result of a completely different way of thinking. It is a three-layer model, not a cascade.
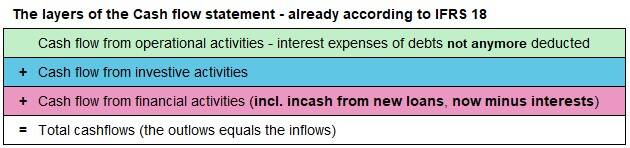
It is based on the 'capital flow calculation' (German: 'Kapitalflussrechnung'), which was not been widely accepted in business management, at least in Germany. For more details, see the section on IFRS 18 below.
The totals of the cash flow statement answer the trivial question:
Do cash inflows, including inflows from new borrowing, equal cash outflows?
Without further analysis, a reader might draw the misleading conclusion that : As long as the company can obtain new loans, outflows will not be a problem.
Unfortunately, this is how most states operate. But companies cannot!
This is how the cash flow statement works according to IFRS 18 :
- mixes own funds with new debts,
- moves interest expenses out of operating activities,
- hides poor operating results, due to transfering interest expenses to financial activities,
- uses three “activities” that are not derived from the four account classes,
- does not show deposits and withdrawals including dividends,
- does not show self‑financing capacity,
- does not show sustainable repayment.