Double-entry Accounting
If you want to become a successful entrepreneur, a capable member of a supervisory board, a good advisor or a good politician, you don't need to know much about accounting theory.
The mathematical fundamentals presented here can be learnt in about two hours. Explain the principles, provide striking examples, and then move on. This will save you time, enabling you to focus on really important business management subjects.
Familiarise yourself with modern coding and the bridge to cash flow 1-3. However, if you want to delve deeper, look at the following accounting theory. This will facilitate your mastery of the fundamentals.
Before digitisation, calculations were performed using mental arithmetic. To make it manageable, traditional bookkeeping used a convention in which each number column contained only one sign, more precisely the positive sign. This convention led to the debit-and-credit entry system. Details on this convention can be found in section 9.2 of the file Business Management – Basics, Indicators, Examples
Modern coding
In practice, today accountants’ work is coding. That is assigning entries with numbers. You will find different code systems. You can interpret a digit as a column:
- 4‑digit codes → thousands of “columns”.
- 5‑digit codes → tens of thousands of “columns”.
Example:
Buying electricity maybe coded with 8518. That means: Virtual column 8518.
This coding allows:
-> detailed in‑year “journal of individual entries”,
-> automatic duplication.
Bill scanning is now in use. That means it is possible to scan bills and record the details of transactions. This partly replaces manual coding.
The bridge to Cash Flow 1, 2 and 3
As already mentioned on the first pages of this website: The four classes of accounts form the basis of accounting. They provide also a direct route to entrepreneurial analysis. They form the basis of cash flow 1–3 and the metric of cash flow 3 metric.
- Profit accounts → Gross Cash Surplus → Cash Flow 1
- Private accounts → Deposits / withdrawals → Cash Flow 2
- Financial accounts → Repayments of debts → Cash Flow 3
- Asset accounts → Depreciation as benchmarks of Cash Flow 3
Accounting theory with Double-entry Table
Since the introduction of calculating machines and the advent of digital computers, accounting has been able to be handled solely with plus and minus, as in all other fields of life, including buying from the local shop, billing work and energy transmission. This is so despite that business management teaching has neglected the change brought about by digitisation. Today, a plus or minus sign can be assigned to each entry, and both signs can appear in the same number column.
In that direction you can find voices around the world. See page Home “Why is this website?" For more details download my article Finally digital – Double-entry
In 1983, I started developing the double-entry tables using only plus and minus. In textbooks I found the four classes of accounts are:
1. Financial accounts.
2. Tangible (or real) asset accounts.
3. Profit accounts (income and expenses).
4. Private/non-company accounts (deposits and withdrawals).
Some combine profit accounts and private/non-company deposit and withdrawal accounts into equity accounts. This gives them three classes of account. Others, like the standard US GAAP financial statement classification, categorise revenue (income) and expenses separately. This results in five account groups. You may see systems with ten groups. However, if you delve deeper, you will always end up with four classes.
The Double-entry Table shown here is perhaps the simplest and most transparent representation of double-entry bookkeeping ever created. In principle, each account only needs one column.
But few columns have been duplicated in the double-entry table shown, such as the current account and the cash desk. This is in order to provide a better overview. It should be clear that the ‘private accounts’ have to be divided into deposits and withdrawals.
The Double-entry Table shown here is perhaps the simplest and most transparent representation of double-entry bookkeeping ever created. In principle, each account only needs one column.
But few columns have been duplicated in the double-entry table shown, such as the current account and the cash desk. This is in order to provide a better overview. It should be clear that "private" accounts have to be divided into deposits and withdrawals.
This Double-entry Table facilitates teaching of accounting theory:
- understand accounting without learning debit/credit,
- teach double‑entry bookkeeping in two hours,
- derive profit,
- understand deposits and withdrawals,
- analyse equity, even if it is negative.
First, a shortened double-entry table is presented to convey the principle.
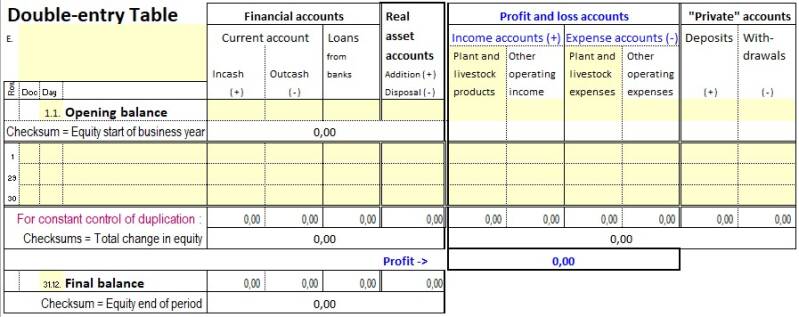
Here is an empty double-entry table with 20 number columns.
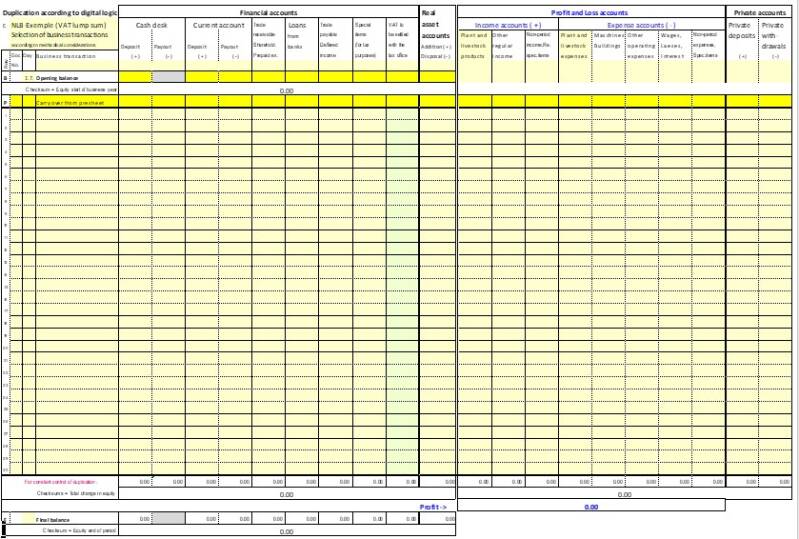
Adapt it to your language and sector—and start testing !
The table is designed to be printed in A3 format or a similar size.
This table contains — or requires :
- The four account classes.
- Plus/minus signs for each entry.
- Duplication rules.
- And — most importantly — checksums.
The checksums are the heart of the system
There are three kinds of checksum ('Quersumme' in German):
1. The checksums on both sides of the table in the third-last lines indicate the equity change.
The two must be exactly equal after every doubled entry!
2. The checksums of the financial accounts plus tangible assets indicate the equity,
once in the opening balance and once in the closing balance.
3. The final line of the profit accounts shows the year's profit.
However, before the entries for assets and special items at the end of the year are finalised, the gross cash surplus is shown.
The following examples reflect these kind of checksums. The lines show a selection of entries from a farm. However, as mentioned previously, the double-entry table is universal.
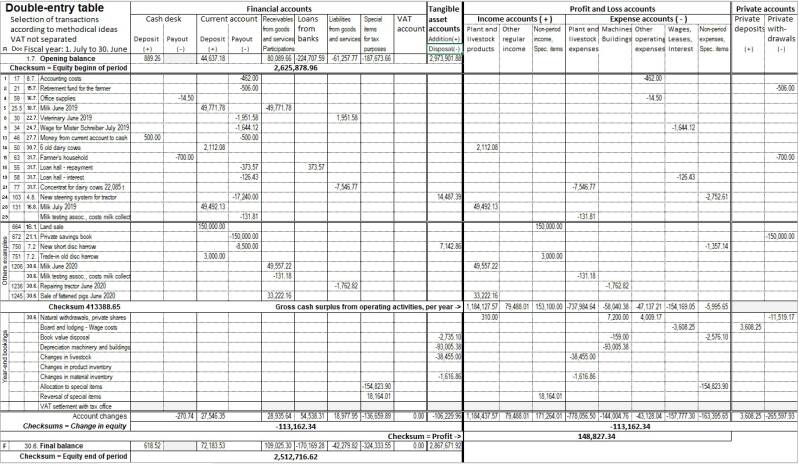
Duplication rules — simple and logical
- Duplication
within financial and tangible asset accounts, or
within profit and private accounts :
If money leaves one account and becomes an asset in another, e.g., buying a machine.
-> money gone → minus
-> machine there → plus
The signs reverse.
- Duplication
across the central vertical line between
financial/assets accounts and profit/private accounts :
If money is earned, e.g., selling a product.
-> money there → plus
-> product sold → plus
The signs remain the same.
The same when money is spent for the company, e.g. for material.
-> money gone → minus
-> material used → minus
The signs remain the same.
Two other examples in the table above:
a) Look at the second line after 'Gross cash surplus'. It demonstrates how double-entry bookkeeping works when a company provides meals for an employee or apprentice. A plus sign appears next to 'withdrawals' and a minus sign appears next to 'wages'. Equity remains untouched, but profit decreases.
b) There are three lines for the different double entries of monthly milk sales.
-> Start of year: once (+) current account, contra-entry (—) receivable account.
-> Normal entry: once (+) current account, contra-entry (+) livestock account.
-> End of year: once (+) receivable account, contra-entry (+) livestock account.
This makes it clear to which booking year the entries belong.
This system provides a logical framework for digital double‑entry bookkeeping theory:
- a theoretical foundation,
- a didactic tool,
- a bridge between conventional accounting theory and modern digital accounting theory.
As has been said: The double‑entry table enables students to grasp the principles of double-entry accounting in about two hours :
-> One hour is spent on the four classes of accounts and the checksums.
-> The other hour is spent on double-entry examples, such as the ones above.