Gross Cash Surplus –> Equity. Over-indebtedness
The first two parts of the annual financial statements always include
- the profit and loss statement (P&L)
- the balance sheet (that is assets, liabilities and equity).
For entrepreneurs, the P&L is primarily – and so it should be for teachers.
Gross Cash Surplus –> Profit
The P&L sequence shown in the following table is used in German agricultural accounting reports. It contains four columns. The author has only separated the presentation of the totals of the columns into four lines - for easier reading.
- Revenues and expenditures (payments) end with Gross Cash Surplus.
- Income and expenses end with Profit.
The gross cash surplus is also the starting point for cash flows - if the 'direct method' is applied.
Gross cash surplus can be monitored throughout the financial year, before final depreciation, inventory valuation, and other year-end works.
Depreciation must be calculated in accordance with tax or commercial law. This leaves considerable scope for tax advisers to be creative. For this reason, cash flows often provide a more reliable picture of a company's financial position than profit alone.
Pay attention to changes in inventory:
an increase in unsold stock increase profit without increasing cash revenues. Gross cash surplus therefore helps reveal the difference between cash generation and period profit.
⭐ Beware of False Friends:
In English income is not profit. Income minus expenses affects profit.
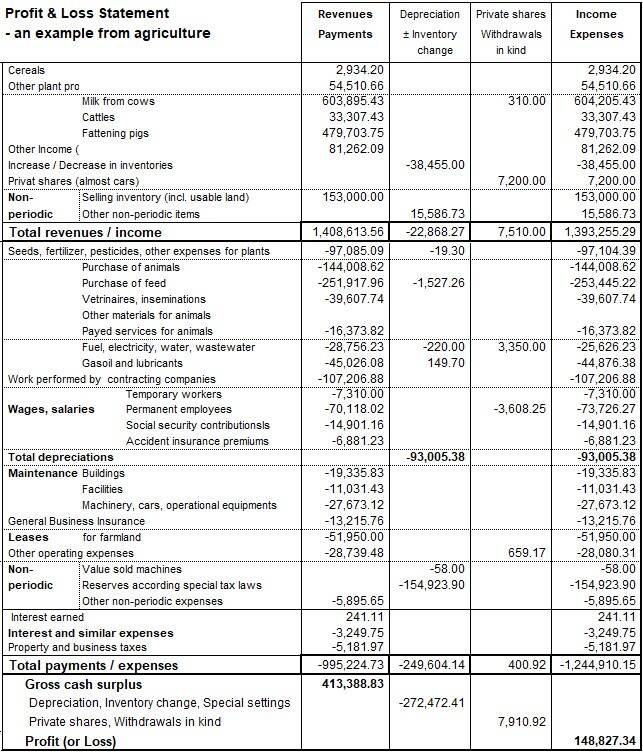
This farm which employs five full-time labourers, has a depreciation value of over 93,000 euros.This is a remarkably large amount compared with the reported profit !
In the examined year, land (where other people want to build houses) was sold for 150,000 euros. Of course, this is an extraordinary amount of cash. German law permits such revenue to be sheltered from tax for reinvestment (in land or buildings) within about two years. See second column.
Profit –> Ordinary Profit
The profit (& loss) statement is the result of bookkeeping.The analyst must transform the accounting statement into an economic profit statement that reveals the Ordinary Profit. The analyst's key task is to identify the necessary adjustments.
In the author's program for analysing and planning JUP PS, you can automatically import the accountant's figures for three or five years. For each year, an adjustment column is provided allowing you to start analysing immediately. See the following table.
Why derive the 'ordinary profit' already here?
It's because of the advantages for the practitioner:
- When he considers the lines, he can make adjustments simultaneously.
- The adjustment column can also be used for reallocations.
- The adjustment column ends up with the 'ordinary profit’.
Some adjustments can be automated, but many still require professional judgement. Even in the age of artificial intelligence, skilled analysts remain indispensable.
Look at the adjustment column in the following table. One example:
In a family business, the son of the owners may receive wages that the accountant records in his ledgers.
However, from an economic viewpoint, you need to know how much ordinary profit is left for the entire family. As shown in the following table, €33,071 of wages are deducted. They are transferred to private (personal) withdrawals.
The JUP PS software neutralises automatically the sale of inventory. However, when it comes to the machines in your company, you may wish to consider whether that figure is truly one-time. Sometimes, specific items within a company can overwhelm programmes. In this case, some additional wording should be included in an advisory letter.
After adjustments, the track for ordinary profit is as follows:
Gross Cash Surplus → Profit → Ordinary Profit.
By the way, the first time I came across the column for adjustments (in German: Bereinigungen) was at the 'Betriebswirtschaftliches Büro' in Göttingen in 1973.
Note that in this presentation, the signs for expenses have been changed from minus to plus - for easier reading.
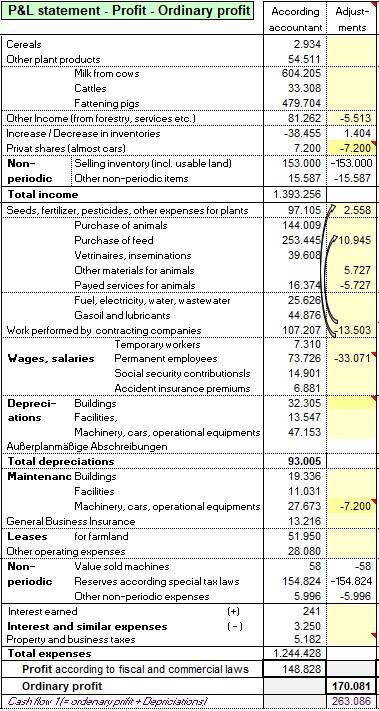
In the adjustment column, you can also see some reallocations (see the arrows). The analyst has indicated some incorrect codings there. Such corrections in the lines are preparatory work for the cost-benefit analysis.
This table already shows the operational cash flow (cash flow 1), using the so-called practitioner's formula.
Cash flow 1 = ordinary profit + depreciation
Adjustments on depreciation?
As you see on the farm example, the depreciation may have a very big impact. It is worth asking whether depreciation reflects a sustainable long-term level. The aim is to obtain reliable figures.
In the long run, there are no significant differences between depreciation according to tax or commercial law and economic reasons. In this farm example, no adjustments were made.
Generally, you should examine the depreciations in individual years carefully.
Here are some explanations. In business management, depreciation is usually calculated linearly. However, according to tax rules, depreciation can generally be legally manipulated. For political reasons, it is often permitted to choose a 'degressive' method of depreciation. Furthermore, a reduction in acquisition costs may be permitted (e.g. for small companies). Companies may even legally transfer depreciation to a period before the time of investment.
However, then depreciation in later years is much reduced, meaning that later profits are artificially higher than they would be with linear depreciation!
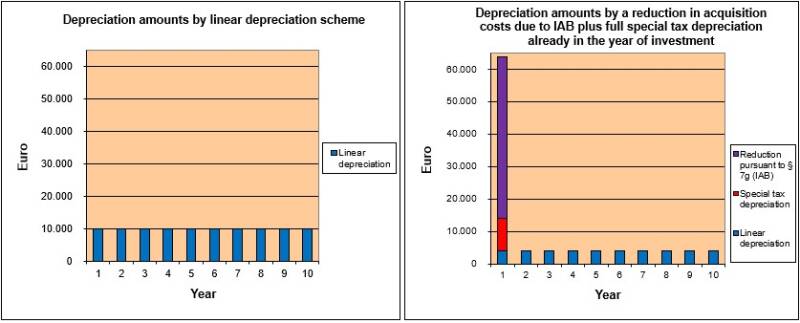
High depreciation can indicate a successful company's growth. However, if the investment has only been made to avoid taxes, this can lead to unbearable debt servicing costs.
Avoid disaster for the business's liquidity and stability!
Equity -> Adjusted equity
Accountants' balance sheets must also be transferred into analysts' balance sheets, using adjustments according to economic rules. The basic formula in the balance sheet is:
Equity = Total Assets - Total Liabilities
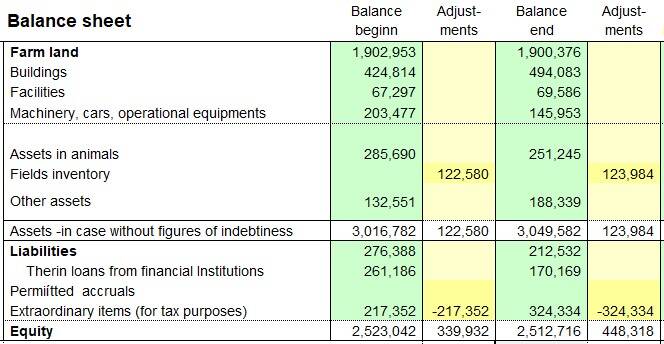
Is such a simplified balance sheet sufficient for analytical work? Yes, it is. Each company is given a detailed balance sheet by its bookkeeping office. The analyst can also make adjustments to this shortened version of the balance sheet.
Only a few adjustments were made to the farmer’s balance sheet shown here.
a) In Germany, there is an option to value the field inventory or not. However, economically, the field inventory has value, at least by the middle of the year (this is the balance sheet date for agriculture in Germany). Therefore, the analyst can add assets of around 123,000 euros for field inventory.
b) Regarding the extraordinary items (see the final lines of the figure), it is proposed that the entire amount is to be neutralised. In this farm example the adjustment column shows an additional equity : about plus €340,000 and plus €450,000 respectively.
In addition to P&L statement and balance sheet, every set of annual accounts must show gross investment, enabling analysts and the supervisory board to assess it.
Assets and equity in an over-indebted business
The convention of 'debit and credit' was first written down by Luca Pacioli in 1494. The reason was mental arithmetic. Ordinary mortals are not able to add up a column of numbers with changing signs. The challenge was to get a system in which no value below zero appeared in a column, even for equity. More on this topic on page "Double-entry accounting" and in section 9.2 Double-entry bookkeeping of Business Managment – Basics, Indicators, Examples.PDF
This convention is still applied in Germany to balance sheets : equity must not have a value of less than zero. To achieve a balance in an over-indebted company, you have to add the amount of debt that is not covered by assets to the assets side! This means that additional assets are created artificially.
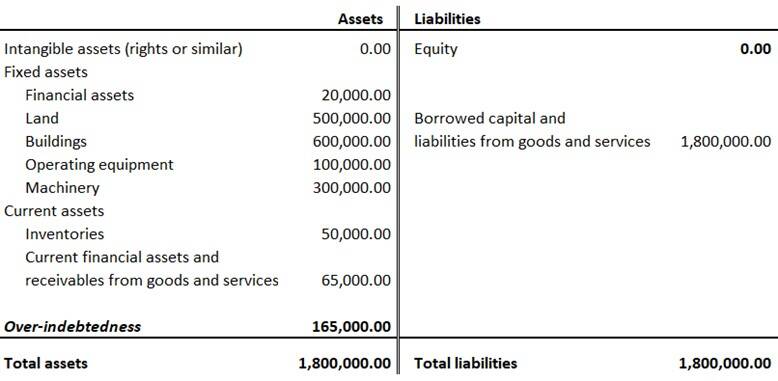
Digital calculators were introduced over 50 years ago. Since then, changing signs in a column of numbers have no longer been a problem, also for equity!
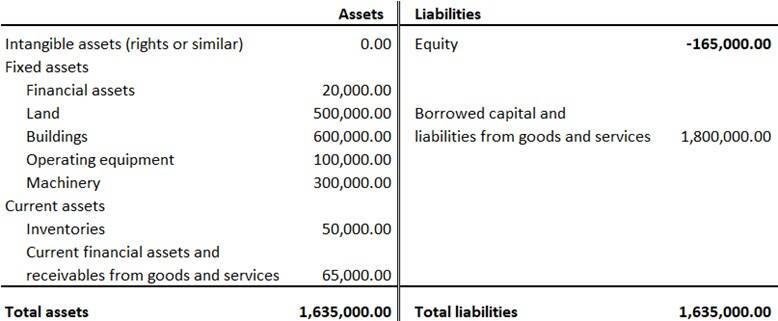
According to the "plus and minus" logic, the total assets are less than the total debts. This logic can and must replace the convention of "debit and credit".